 Skip to content

OTL 2026: How Nigeria’s petroleum can fuel industrialization, build energy hub

- NMDPRA pushing fuel diversification, regional market devpt.
Sopuruchi Onwuka
Nigeria is seeking to reposition itself from a country struggling with domestic energy supply deficits and dependence on imported petroleum products into a regional energy hub capable of supplying West Africa with gas, refined petroleum products and associated energy services.
But achieving that ambition will depend on more than expanding refining capacity and exploiting its vast hydrocarbon resources.
It will require reliable infrastructure, predictable regulation, transparent pricing, adequate strategic reserves and closer integration of regional energy markets.
The Nigerian Midstream and Downstream Petroleum Regulatory Authority (NMDPRA) has outlined a roadmap to achieve this transition, combining ongoing infrastructure projects with reforms designed to improve market efficiency, strengthen energy security and attract fresh investment into the oil and gas industry.
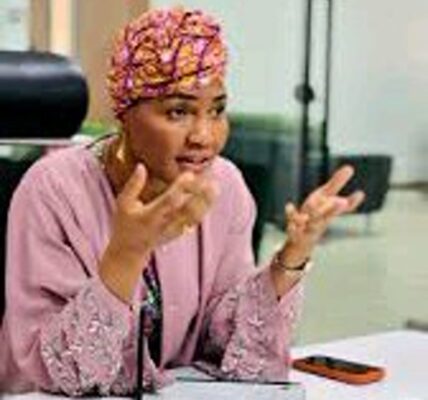
Speaking at the OTL Africa Downstream Energy Week 2026 at the Oriental Hotel, Lagos, the Authority’s Chief Executive, Rabiu A. Umar, said Nigeria’s energy future must be built around the twin objectives of secure supply and shared prosperity.
In his keynote address, titled “Secure Energy, Shared Prosperity,” Umar presented a picture of an industry making progress in infrastructure development and regulatory reform but still facing substantial gaps in domestic supply, gas utilisation and product storage.
His central argument was that Nigeria has the resource base, market size and emerging infrastructure to become a regional energy hub, provided it can translate these advantages into dependable supply, competitive markets and cross-border cooperation.
The scale of the opportunity is considerable as Nigeria holds about 215 trillion cubic feet (Tcf) of natural gas, the largest reserves in Africa, and approximately 37 billion barrels of crude oil. Yet these resources have not fully translated into the reliable and affordable energy supply needed to support domestic industrialisation, while also positioning the country as a dependable supplier to neighbouring economies.
The challenge, therefore, is not simply to produce more hydrocarbons but to develop the infrastructure and market arrangements required to process, transport and distribute them efficiently.
Gas infrastructure is particularly central to this ambition. Nigeria has installed gas processing capacity of 16.2 billion cubic feet per day (Bcf/d), but only about 52 per cent is being utilised. This underutilisation points to the gap between installed capacity and the effective delivery of gas to industries, power generation facilities, processing plants and export markets.
Closing that gap will require investments in pipelines, processing facilities and distribution networks, as well as more effective coordination between producers, transporters and consumers.
Umar identified several major pipeline projects nearing completion, including the Obiafu-Obrikom-Oben (OB3) pipeline, the East-West Offshore Gas Gathering System (ELPS) midline compressor, the Ajaokuta-Kaduna-Kano (AKK) pipeline, the Odidi-Warri expansion and the Escravos-Odidi pipeline.
As of September 2026, OB3 was 96 per cent complete, while the ELPS midline compressor stood at 97 per cent. The AKK pipeline was 84 per cent complete, the Odidi-Warri expansion had reached 78 per cent, and the Escravos-Odidi project was 30 per cent complete.
The significance of these projects extends beyond the addition of pipeline capacity. They are intended to improve connectivity between gas-producing areas in southern Nigeria and underserved markets in the north, where access to dependable energy remains a major constraint on industrial and commercial activity.
According to Umar, the completion of the AKK and OB3 pipelines would add about 2.0 Bcf/d to the existing 2.2 Bcf/d capacity of the ELPS system, raising total gas transportation capacity to approximately 4.2 Bcf/d.
Such an expansion would strengthen the movement of gas across the country, potentially supporting power generation, industrial development, fertiliser production and other gas-based businesses. It would also provide a stronger foundation for Nigeria to supply regional markets through interconnected gas infrastructure.
However, the benefits will depend on the timely completion and commissioning of the projects, the availability of gas supplies and the commercial arrangements required to move the commodity from producers to end users.
Nigeria’s gas utilisation figures demonstrate why these issues matter. Of the 8.394 Bcf/d of gas processed, 62 per cent went to midstream and downstream activities, while 38 per cent was used upstream or flared.
The breakdown showed that 2.066 Bcf/d went to the domestic market, 2.760 Bcf/d was supplied to Nigeria LNG Limited (NLNG), 0.279 Bcf/d went to the Escravos Gas-to-Liquids (EGTL) facility, and 0.134 Bcf/d was exported through the West African Gas Pipeline (WAGP).
These figures illustrate the competing demands on Nigeria’s gas resources. Domestic industries and power generators require reliable supplies, while LNG exports and regional pipeline deliveries offer opportunities to earn foreign exchange and strengthen Nigeria’s position in international energy markets.
Reducing gas flaring and directing more gas towards productive use could help reconcile these competing priorities. It would also support the development of gas-based industries, including fertiliser manufacturing, petrochemicals and liquefied petroleum gas (LPG) processing.
Demand for LPG is already exposing the consequences of insufficient supply infrastructure. Umar said consumption had risen 33 per cent above the benchmark, reaching 5.2 kilotonnes per day (KT/D), against supply of 4.7 KT/D.
The shortfall underscores the need to expand domestic processing, storage and distribution capacity if Nigeria is to meet growing demand for cleaner cooking fuels while reducing reliance on supply from external markets.
Compressed natural gas (CNG) also offers opportunities in the transport sector, while commercialising gas that would otherwise be flared could create additional revenue streams and improve the utilisation of existing resources.
For Nigeria, the strategic advantage lies in developing an integrated gas market in which production, processing, transportation and distribution reinforce one another. For West Africa, a more dependable Nigerian gas supply could help support electricity generation, industrial activity and regional energy trade.
Yet infrastructure expansion alone cannot guarantee energy security. The country’s petroleum product supply position highlights the importance of maintaining adequate inventories and ensuring that domestic demand is matched by reliable supply.
Umar disclosed that Nigeria had 53.2 days of aviation fuel stocks and 49.7 days of diesel stocks as of September 2026, both above the 30-day threshold. Petrol stocks stood at 23.9 days, while LPG stocks were equivalent to 15.9 days, leaving both products below the desired level.
The figures reveal an uneven level of preparedness across the downstream market. While aviation fuel and diesel inventories provide a relatively stronger buffer against supply disruptions, petrol and LPG require greater attention to storage, replenishment and distribution.
Nigeria supplied an average of 38.7 million litres of petrol per day against consumption of 44.4 million litres, with the difference met from existing stocks.
This supply gap illustrates why the country’s transition towards greater domestic refining capacity must be accompanied by a more comprehensive approach to product logistics and strategic reserves. Even where local refineries can supply significant volumes, inadequate storage or distribution infrastructure can undermine the reliability of the market.
Umar said feedstock security had been supported through the Domestic Crude Supply Obligation (DCSO) and the Naira-for-Crude arrangement, mechanisms intended to improve access to crude oil for domestic refiners.
The effectiveness of these arrangements will be critical to ensuring that available refining capacity translates into consistent domestic supply. Refiners require predictable access to crude, while marketers and distributors need dependable product availability and efficient logistics to serve consumers.
The Authority’s commitment to strengthening strategic stocks and maintaining 30 to 45 days of supply sufficiency reflects an understanding that energy security must be measured not only by production volumes but also by the industry’s ability to withstand disruptions.
Beyond physical infrastructure, Umar’s address highlighted the growing importance of regulatory reform in shaping the country’s energy market.
A major development was the launch of Revision 2 of the Network Code on October 26, 2026. First introduced in 2020 to establish an open-access framework for gas transmission and revised in 2024, the Code is intended to improve transparency and access to Nigeria’s gas transportation network.
Under the revised framework, the Authority is advancing open and non-discriminatory access to the gas network, alongside transparent transport tariffs that reflect costs. These provisions are intended to improve the terms on which gas producers and buyers access pipeline infrastructure, reducing the scope for discriminatory treatment and making transportation charges more predictable.
The reform has also been associated with a 30 per cent reduction in imbalance on the Western Network during the first half of 2026, as well as improvements in measurement at gas entry and exit points.
These developments suggest progress towards a more disciplined gas transportation system in which quantities delivered and received can be measured more accurately and imbalances managed more effectively. For investors, transparent tariffs and reliable measurement are important because they improve commercial certainty and reduce disputes over volumes and transportation charges.
The significance of the Network Code extends beyond gas producers and pipeline operators. A transparent and accessible transportation system can encourage greater participation by industrial consumers, gas distributors and other market players, while helping to unlock existing processing capacity.
The challenge for the NMDPRA will be to ensure that these rules are implemented consistently and that open access translates into practical commercial opportunities rather than remaining a regulatory objective.
The Authority is also pursuing reforms to promote fair competition, protect consumers and improve product quality. These include a memorandum of understanding with the Federal Competition and Consumer Protection Commission (FCCPC) to coordinate enforcement and consumer protection.
Following consultations held on September 22, 2026, the Authority has also developed draft Anti-competition Regulations 2026, signaling a stronger regulatory focus on market conduct and competitive practices.
The proposed regulations could become an important instrument for addressing practices that restrict competition or disadvantage market participants. Their effectiveness, however, will depend on clear provisions, consistent enforcement and the ability of regulators to distinguish legitimate commercial conduct from practices that undermine competition.
Product quality assurance is another priority. The NMDPRA has undertaken field quality testing in Port Harcourt and entered into a tripartite memorandum of understanding with Bureau Veritas and Ace Energy and Power Solutions to establish a National Reference Laboratory to international standards set by the International Organization for Standardization (ISO).
The Port Harcourt laboratory has been upgraded, while nine other laboratories are being modernised.
Strengthening laboratory capacity is important for verifying the quality of petroleum products, improving regulatory oversight and protecting consumers from substandard supplies. It could also support Nigeria’s regional ambitions by providing more credible quality assurance for products traded across borders.
A market aspiring to become a regional supply hub must be able to demonstrate that its products meet recognised standards and that its quality-control systems are reliable. Without such confidence, domestic refiners and exporters could face additional barriers in neighbouring markets.
The Authority is also gridding the country to expand Gas Distribution Licences (GDLs), a measure intended to improve the framework for gas distribution and encourage wider access to gas.
Taken together, these initiatives suggest that the regulatory agenda is moving beyond licensing and compliance towards a broader framework covering market access, competition, product quality, infrastructure development and consumer protection.
The next test is whether the reforms can deliver a sufficiently predictable business environment to attract the investment required to expand supply and distribution.
Umar estimated that Nigeria would need between $30 billion and $50 billion in fresh oil and gas investment to 2030, particularly in gas processing, fertiliser production, LPG and flare-gas commercialisation.
The investment requirement reflects the scale of the infrastructure gap, but it also points to opportunities for private capital. With only about 52 per cent of installed gas processing capacity currently utilised, investors could benefit from projects that improve the availability of gas and connect existing facilities to new markets.
Capacity expansion plans provide an indication of the scale of the opportunity. NLNG’s capacity is projected to rise from 22 million tonnes per annum (MMTPA) to 30 MMTPA with Train 7. Indorama’s fertiliser capacity is expected to increase from 4.38 MMTPA to 5.84 MMTPA with Train 4, while the LPG market is projected to grow from 1.8 MMTPA to 4.0 MMTPA.
Gas transportation capacity is also projected to increase from 2.2 Bcf/d to 4.2 Bcf/d as key infrastructure projects are completed.
These expansions could deepen domestic gas utilisation, strengthen exports and create additional demand for transportation, storage and distribution services. They could also support a wider industrial ecosystem around gas processing, fertiliser production and other energy-intensive activities.
Product logistics represent another investment opportunity. Umar identified depots, jetties, coastal shipping and the revival of petroleum product pipelines as areas open to public-private partnerships.
The emphasis on public-private partnerships recognises that government and regulatory institutions cannot independently finance and deliver all the infrastructure required for an integrated energy market. Mobilising private capital will therefore depend on credible project structures, commercially viable tariffs, predictable rules and confidence that investors will be treated fairly.
The regional dimension of the strategy is equally important. Nigeria’s domestic market is large, but the ambition to become an energy hub rests partly on the ability to supply neighbouring countries through reliable trade arrangements and compatible regulatory systems.
At present, differences in product standards, licensing requirements, quality-control procedures and market rules can complicate cross-border trade. Greater regulatory coordination could reduce these obstacles, improve transparency and create a more predictable environment for regional suppliers and buyers.
To address this challenge, the NMDPRA has proposed a phased roadmap for West African energy market integration extending to 2030.
The first phase, covering 2026 and 2027, is designed to align regulatory frameworks through enforcement of the Economic Community of West African States’ 50-parts-per-million sulphur standard for fuels, the introduction of a regional data-sharing protocol and joint border quality checks.
The proposed measures would help improve consistency in fuel quality, strengthen information exchange among regulators and reduce opportunities for substandard products to move undetected across national borders.
The second phase, scheduled for 2028 and 2029, would focus on deeper integration through mutual recognition of licences, common codes for cross-border pipelines and storage facilities, and the application of African Continental Free Trade Area rules to refined petroleum products.
Mutual recognition of licences could reduce duplication for companies operating in multiple markets, while common infrastructure codes could simplify the development and operation of cross-border facilities. Applying AfCFTA rules to refined products would also support the broader objective of reducing barriers to intra-African trade.
The final phase, targeted for 2030, envisages coordinated regional strategic stocks, a pathway towards 10-parts-per-million AFRI-6 fuels and the establishment of a credible West African reference price.
Coordinated strategic stocks could strengthen the region’s collective ability to respond to supply disruptions, while cleaner fuel standards would improve product quality and environmental performance. A credible regional reference price could also improve price transparency and provide a more reliable benchmark for commercial transactions.
Umar, however, stressed that integration should not be confused with the surrender of national priorities.
“Convergence, not uniformity: each country keeps the right to secure supply to its own citizens,” he said.
The distinction is important because regional integration will only be sustainable if participating countries can pursue shared market objectives without compromising their domestic energy security. For Nigeria, that means ensuring that regional exports complement rather than undermine domestic supply obligations.
It also means building a market in which neighbouring countries have confidence in the reliability of Nigerian supplies, the transparency of pricing arrangements and the consistency of regulatory enforcement.
To support these objectives, Umar outlined five commitments by the Authority: maintaining 30 to 45 days of supply sufficiency and developing a National Strategic Stock; ensuring reliable feedstock through the DCSO and Naira-for-Crude arrangements; accelerating infrastructure development through public-private partnerships and the Midstream and Downstream Gas Infrastructure Fund (MDGIF); providing predictable and efficient licensing while promoting competition; and publishing monthly market data.
The commitments are intended to strengthen the connection between regulatory policy and measurable market outcomes. Adequate stocks would improve resilience, reliable feedstock would support refining and processing, infrastructure financing would expand supply networks, and transparent licensing and market information would improve investor confidence.
Umar said the initiatives would be delivered through Project NEXUS, which he described as a framework for a firm, fair and fast regulator.
The programme’s significance will ultimately be judged by whether it reduces regulatory uncertainty, improves access to infrastructure, strengthens market competition and accelerates investment in productive capacity.
He called on refiners to prioritise the domestic market, marketers and logistics companies to invest in storage and fair dealing, financiers to support infrastructure development, and host communities and security agencies to protect energy assets. He also urged African partners to align regulatory frameworks in pursuit of a more integrated regional market.
These appeals reflect the reality that Nigeria’s regional energy ambitions cannot be delivered by the regulator alone. Refiners must maintain reliable production, marketers must develop distribution networks, financiers must provide long-term capital, and governments must ensure that energy infrastructure is protected from vandalism and disruption.
Ultimately, Nigeria’s transition from an importer to a regional energy hub will depend on its ability to close the gap between installed capacity and actual supply, between regulatory ambition and effective implementation, and between national energy development and regional market integration.
The country has substantial hydrocarbon reserves, expanding refining and processing opportunities, major pipeline projects approaching completion and a regulatory programme increasingly focused on transparency, competition and quality assurance. These are important foundations for the transition.
But the persistent shortfall in petrol and LPG stocks, underutilised gas processing capacity and the investment required to expand transportation and distribution networks show that significant work remains.
For Nigeria, the opportunity is to turn its resource advantage into a more reliable domestic energy system and a competitive regional supply business. For West Africa, a better-connected Nigerian market could provide the foundation for more secure fuel supplies, greater gas utilisation and stronger cross-border energy trade.
The objective, as Umar’s address suggests, is not simply to export more petroleum products or gas. It is to build a system in which infrastructure, market rules and regional cooperation reinforce one another, enabling Nigeria to convert its energy resources into shared economic benefits.
That is the test that will determine whether the ambition of moving from importer to regional energy hub becomes a lasting market reality or remains a policy aspiration.